Money
Open banking may favour Canada’s Big Six as much as fintech challengers
CP roundup: consumer tools unlikely before late 2027; Finance pegs $13.2B in benefits against $458M in costs as screen scraping persists.
Published: October 4, 2026 · Updated: October 4, 2026 · 2 min read
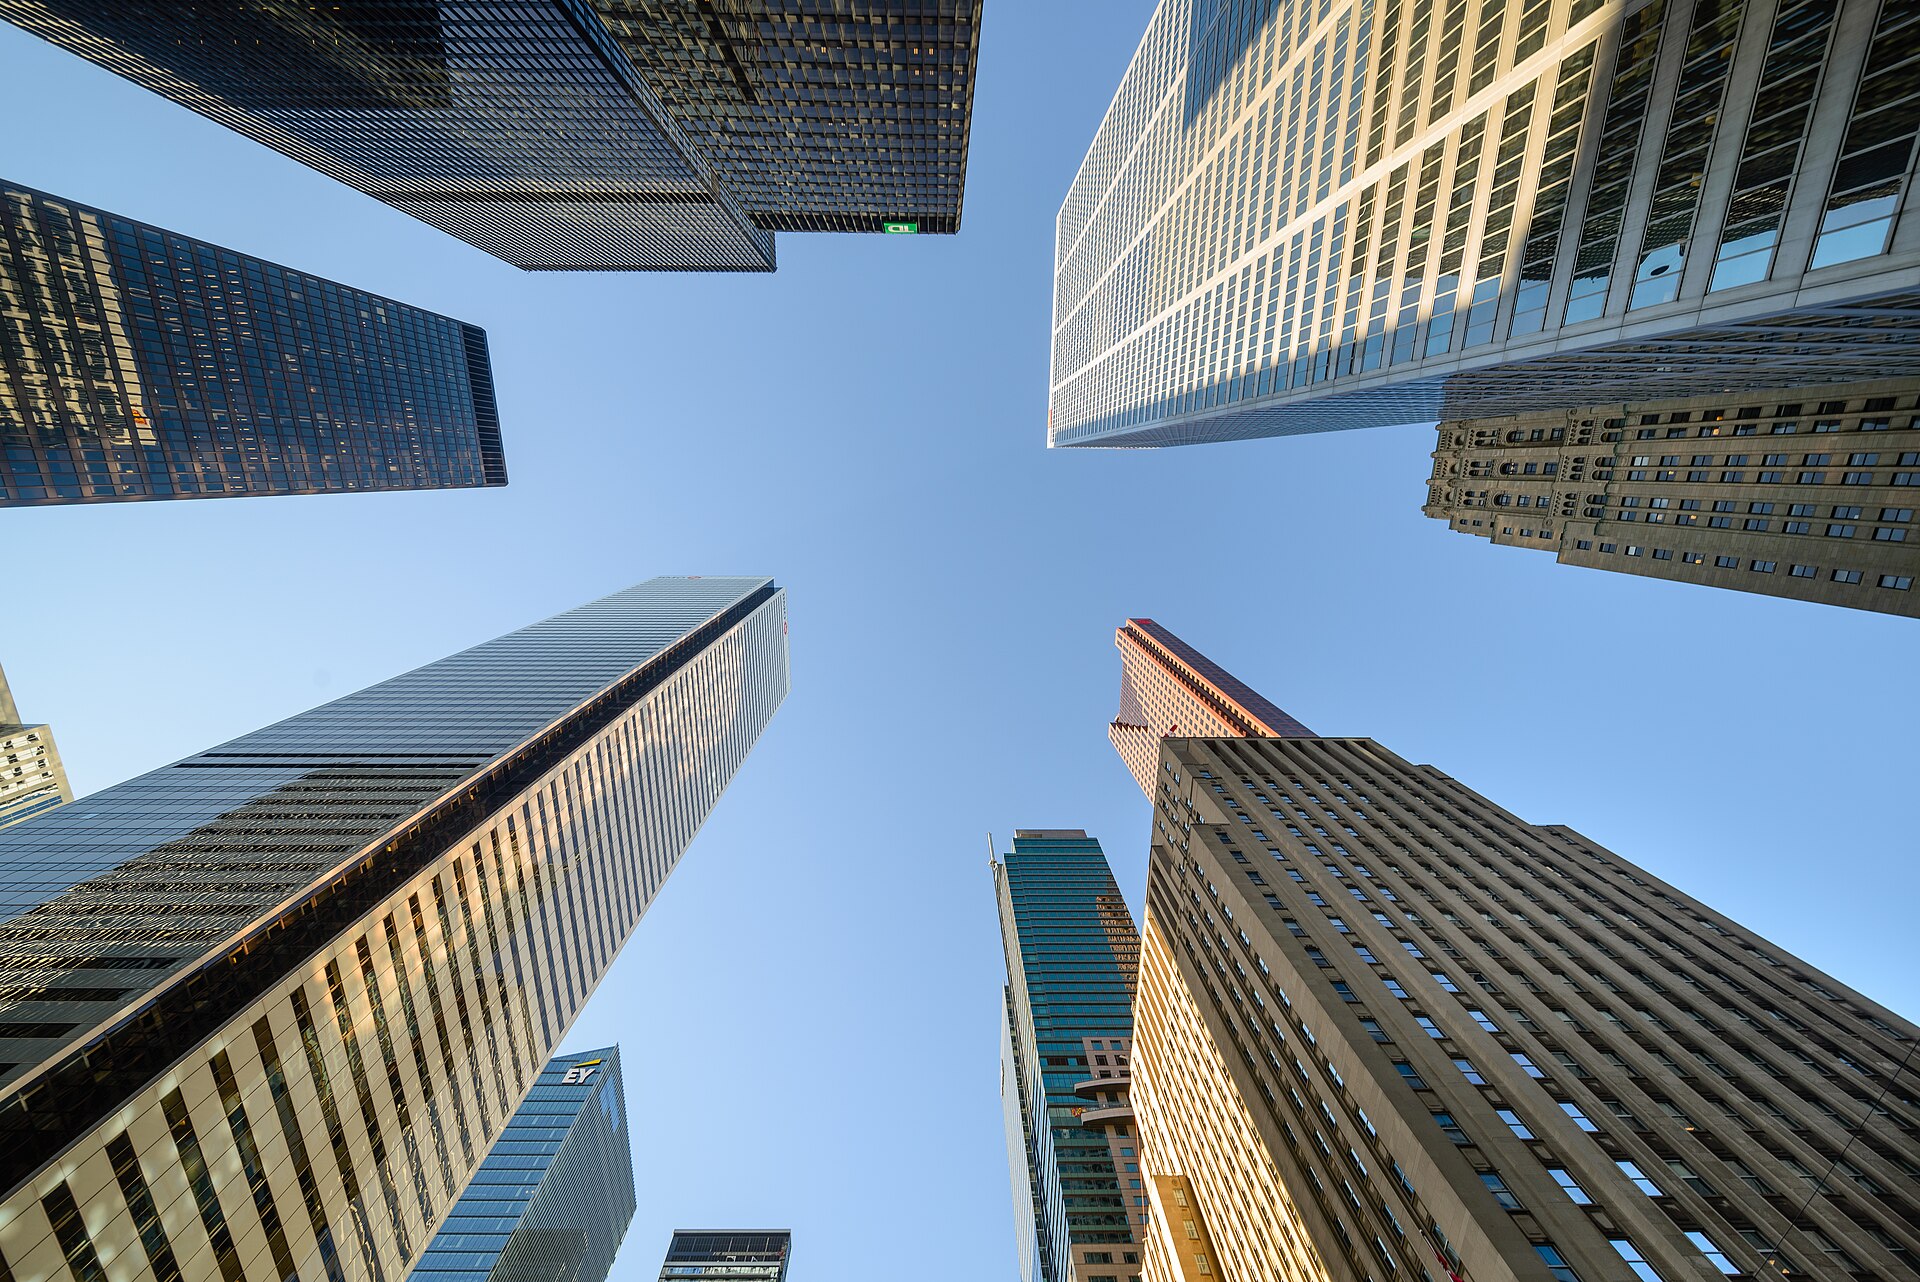
Canada’s long-delayed open-banking project is finally moving from legislation to implementation — and a new Canadian Press roundup published Sunday argues the Big Six banks may have as much to gain as to lose.
Open banking — Ottawa’s preferred label is consumer-driven banking — lets people and businesses securely share financial data across lenders so they can see deposits, investments and insurance in one place and switch products more easily. Global News reported Mark Schofield of Boston Consulting Group describing it as the ability to build a full personal balance sheet from multiple institutions. The Department of Finance’s draft regulations, consulted on through August, estimate roughly $457.7 million in implementation costs over a decade against about $13.2 billion in projected consumer and business benefits. Finance also estimates some nine million Canadians already use riskier “screen scraping,” handing credentials to third-party apps.
Jefferies analyst John Aiken told CP he does not see an immediate “tidal wave” for incumbents, but warned none of the large banks appear fully ready even for stage one and that disruption could erode market share over 10 to 15 years. He also flagged an offensive opportunity: banks could see customers’ investments held elsewhere and pitch to bring them in-house. York University’s Henry Kim noted Canada’s banking oligopoly — the Big Six held more than 90 per cent of banking assets as of late 2025 — gives lenders room to buy or copy successful fintechs. Steve Boms of the Financial Data and Technology Association said consumer access is unlikely before late 2027, and that once frameworks mature abroad lenders often shift from defence to using permissioned data to expand credit access.
The Canada Gazette draft Consumer-Driven Banking Regulations put the Bank of Canada in charge of accreditation and common rules under the Consumer-Driven Banking Act. The Norton Rose Fulbright summary notes staggered force dates and that scheduled big banks can be mandated to participate without the same accreditation path as fintechs. The Canadian Bankers Association told CP it supports a phased, interoperable framework that preserves system stability.
For households, the near-term story is still preparation, not a new app on your phone. When tools do arrive, the competitive question will be whether dashboards and switching friction finally favour challengers — or simply give the largest data holders another growth channel.
This article is for general information only and is not investment advice.
Sources: Global News / Canadian Press; Canada Gazette — Consumer-Driven Banking Regulations; Norton Rose Fulbright; DLA Piper.
Sources
- Global News · other
- Canada Gazette · other
- Norton Rose Fulbright · other
- DLA Piper · other
Newsletter
News. Context. What matters.
One essential briefing, written for people who would rather understand the story than scroll it.
Unsubscribe anytime. We don’t sell addresses.
Recommended
Money
Canadian dollar hovers near 70 U.S. cents as Canada–U.S. yield gap hits widest since 2025
The loonie’s fourth weekly decline and a roughly 157-basis-point two-year spread keep pressure on import prices ahead of October’s BoC and Fed decisions.
Money
BoC and OSFI tell banks overnight SLF draws are routine, not a stress signal
Joint statement accompanies Gravelle remarks on upsizing two-week repos as CORRA runs ~5 bps above the 2.25% overnight target.
Money
UBS, Manulife and Oxford join calls for Bank of Canada October rate hike
After seven holds at 2.25%, forecasters now see a 25-basis-point move on Oct. 28 as inflation risks rise; TSX snapped a four-day slide Friday.