Money
BMO and Scotiabank lift fixed mortgage rates as bond yields climb, adding to renewal pressure on pandemic-era borrowers
BMO’s standard five-year fixed rate rose to 5.14 per cent on Wednesday, days after RBC’s increases. All of the Big Six banks have now raised some fixed rates since early September, and the C.D. Howe Institute says 2020-21 borrowers are renewing in a vastly different environment.
Published: October 7, 2026 · Updated: October 7, 2026 · 3 min read
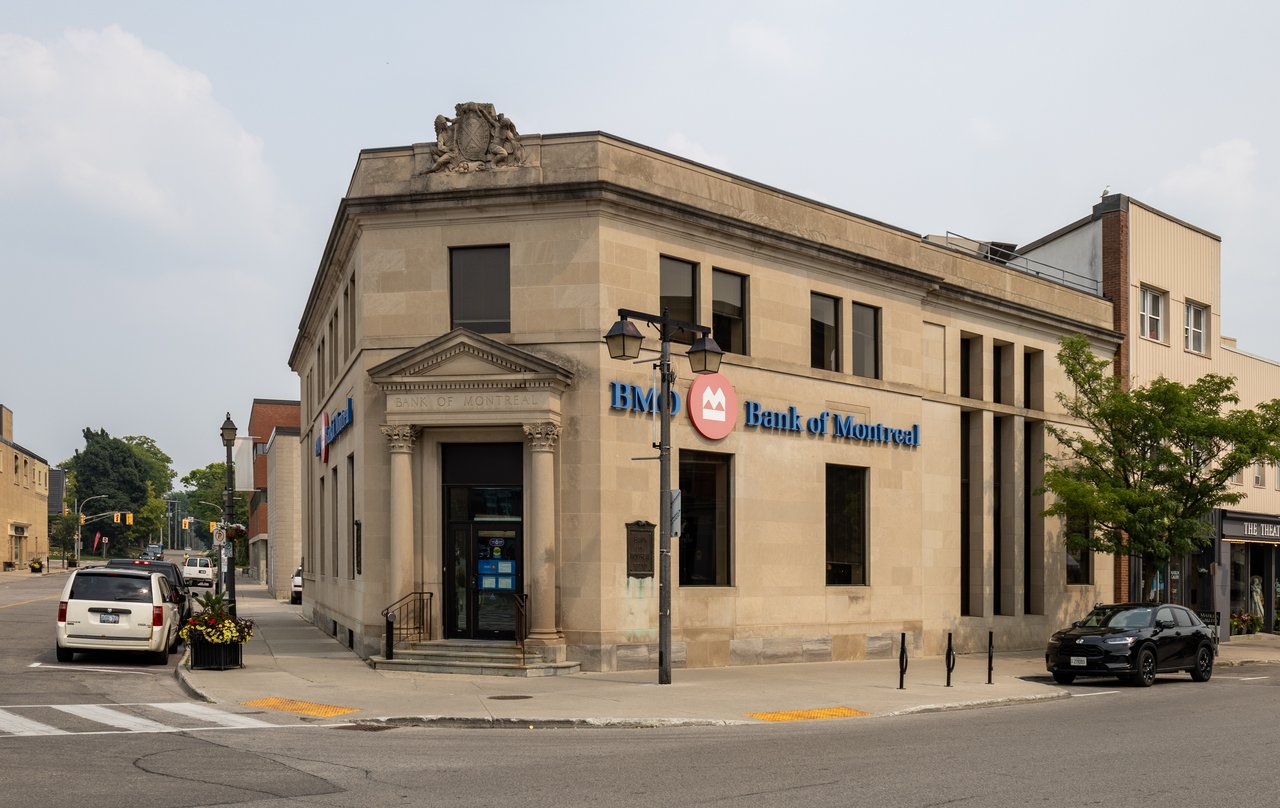
BMO has raised several of its publicly advertised special mortgage rates, the latest in a run of increases at Canada’s largest banks as bond yields stay elevated, Canadian Mortgage Trends reported Wednesday. The bank lifted its three-year fixed rate by 20 basis points to 4.94 per cent and its standard five-year fixed rate by the same amount to 5.14 per cent. Its high-ratio five-year rate rose 15 basis points to 4.99 per cent, and its uninsured hybrid rate rose 10 basis points to 4.62 per cent. Scotiabank also raised its advertised two-year fixed rate by 15 basis points to 5.14 per cent.
The moves follow increases at RBC earlier this week, when the bank raised fixed rates by 10 to 20 basis points across its one- through five-year terms and narrowed its five-year variable-rate discounts from prime by 20 basis points for new borrowers, the same outlet reported. Those changes came after recent hikes at CIBC and TD. Since early September, all of the Big Six banks have raised at least some fixed rates, with cumulative increases of about 10 to 50 basis points across many two- to five-year terms. Some of the largest moves have been at TD and RBC, where several terms have risen by 40 to 50 basis points. CIBC’s rates are generally about 20 basis points higher, while increases at BMO, National Bank and Scotiabank have mostly ranged from about 10 to 30 basis points. The figures are special rates advertised directly by the banks, not rates available through mortgage brokers.
The pressure is coming from the bond market rather than the central bank. The Government of Canada five-year bond yield, an important benchmark for fixed mortgage funding costs, was around 3.624 per cent shortly after noon Wednesday, nearly three basis points above Tuesday’s close of 3.595 per cent, after touching 3.674 per cent earlier in the day as rising oil prices and renewed inflation concerns fed another selloff across global bond markets. It had eased early in the week from a late-September 52-week high of 3.729 per cent. The Bank of Canada, meanwhile, has kept its target for the overnight rate at 2.25 per cent at every decision this year, most recently on Sept. 2.
That gap matters most for households coming up for renewal. In an Oct. 5 note, the C.D. Howe Institute said mortgages taken out in 2020 and 2021, when five-year Government of Canada bond yields were below one per cent, are coming up for renewal, and some already have. Those renewals are set to occur in “a vastly different environment,” with the five-year yield now at 3.7 per cent, the think tank said. Because Canadian and U.S. bond markets are closely integrated, rising U.S. yields tighten financial conditions in Canada even when the Bank of Canada leaves its overnight rate target unchanged. “For renewing households, that means higher payments, raising concerns about household finances and financial system stability.”
Longer-term yields have climbed too. The 10-year Government of Canada yield rose to 3.99 per cent from 3.45 per cent at the start of July, and the two-year yield to 3.37 per cent from 2.76 per cent, according to Morningstar data cited by Canadian Mortgage Professional, which said a primary driver was the Iran war’s effect on energy costs. In the United States, the 10-year Treasury yield climbed to 5.3 per cent from 4.5 per cent, its highest level since 2002. The lowest insured five-year fixed mortgage rate available as of Wednesday stood at 4.34 per cent, the publication said, citing Ratehub.ca.
Signs of strain are already showing in credit data. Mortgage delinquency balances rose 32 per cent year over year nationally in the first quarter of 2026 and 52 per cent in Ontario, according to an Equifax Canada report cited by Canadian Mortgage Professional, which also said approximately 33 per cent of Canadian mortgage holders are expected to face higher monthly payments by the end of 2026. Not every borrower is struggling. Taz Zaide, a Toronto-based mortgage broker, told the publication that his renewal clients had largely managed the transition. “All the clients that we've had who've been up for renewal have basically just been fine with qualification,” he said.
This article is general information and is not investment advice.
Sources: Canadian Mortgage Trends: BMO hikes 3- and 5-year mortgage rates (Oct. 7, 2026); Canadian Mortgage Trends: RBC becomes latest big bank to raise mortgage rates (Oct. 6, 2026); C.D. Howe Institute: Higher Bond Yields Set to Raise Mortgage Payments for Canadians (Oct. 5, 2026); Canadian Mortgage Professional; Bank of Canada: Policy interest rate.
Sources
- Canadian Mortgage Trends: BMO hikes 3- and 5-year mortgage rates · news
- Canadian Mortgage Trends: RBC becomes latest big bank to raise mortgage rates · news
- C.D. Howe Institute: Higher Bond Yields Set to Raise Mortgage Payments for Canadians · research
- Canadian Mortgage Professional · news
- Bank of Canada: Policy interest rate · government
- · other
Newsletter
News. Context. What matters.
One essential briefing, written for people who would rather understand the story than scroll it.
Unsubscribe anytime. We don’t sell addresses.
Recommended
Money
Canada’s average asking rent slips to $2,034 as annual declines stretch to two full years, Rentals.ca and Urbanation say
September’s asking rent was down 4.2 per cent from a year earlier and 9.2 per cent below the May 2024 peak. Condo rents fell hardest, while Urbanation says Toronto and Vancouver are showing signs of stabilizing.
Money
Housing Tradeoffs That Actually Move the Needle (Canada, October 2026)
Re/Max finds two in three Canadians would compromise to afford a home while affordability relief fades. Here is a SeriousPick matrix for which tradeoffs are strategy — and which are self-sabotage.
Money
How People Actually Earn Money With AI in 2026 (Without Becoming a Guru)
Nearly half of AI users say they have earned money with AI. Most “AI income” content is a funnel. Here are paths that survive SeriousPick skepticism.